Buy Now Pay Later and Your Home Loan: What Lenders Look At
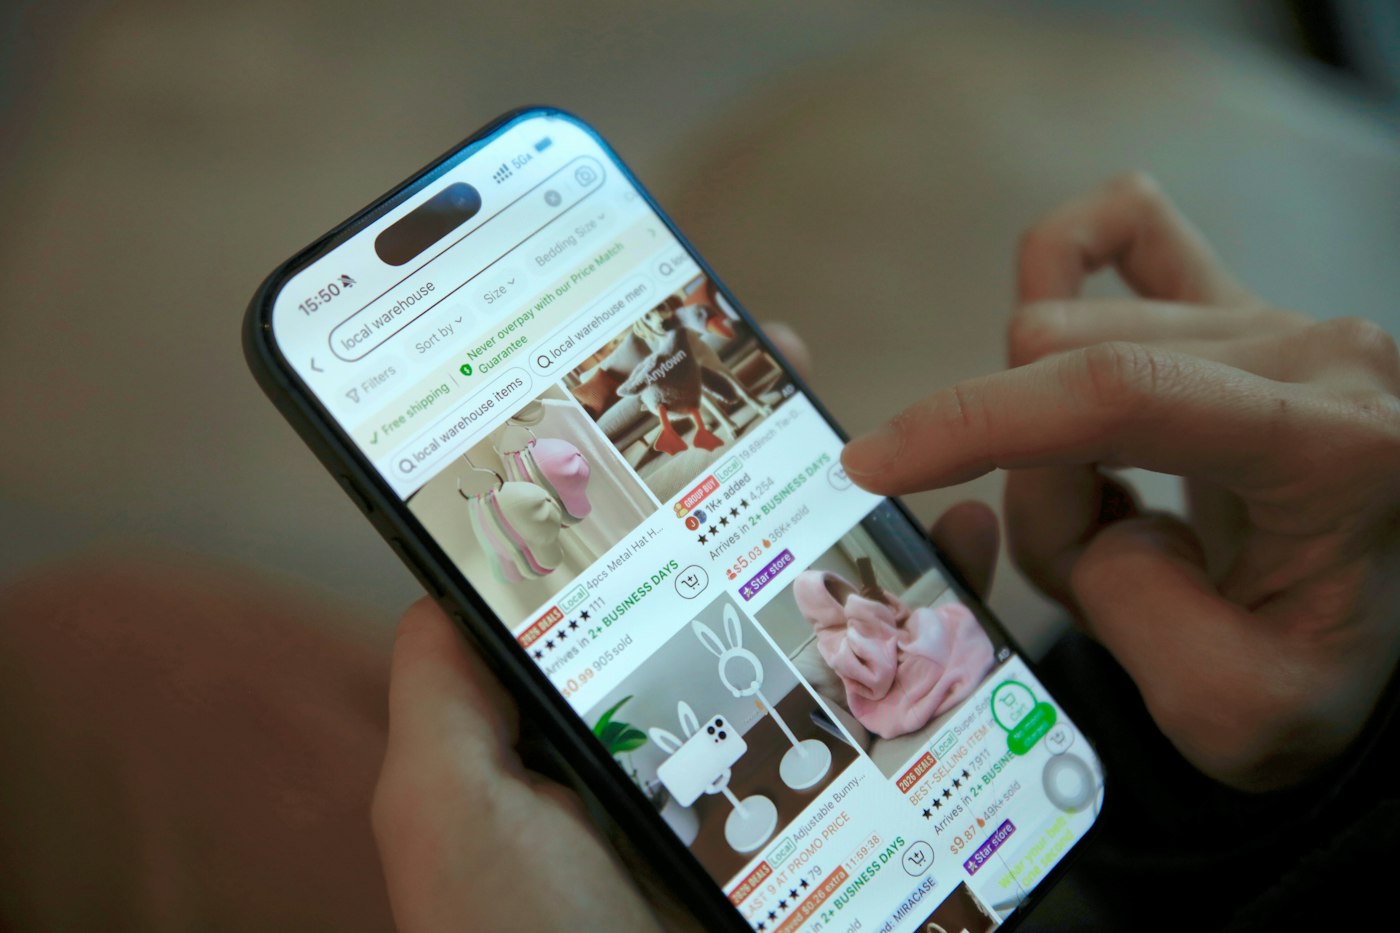
Buy now pay later (BNPL) services make it easy to split purchases into instalments. Used occasionally and paid on time, they’re rarely a problem. But regular BNPL use can affect how a lender views your home loan application, and the rules changed recently.
BNPL is now regulated credit
From 10 June 2025, buy now pay later became regulated under Australian credit law. Providers now need an Australian credit licence, must assess whether the credit is suitable for you, and belong to the Australian Financial Complaints Authority (AFCA). In practice, BNPL looks more like other forms of credit than it used to, including on your credit file.
How lenders look at BNPL
- Your bank statements: lenders review recent statements, and frequent BNPL repayments show up clearly
- Your living expenses: regular BNPL use can suggest spending is higher than your stated budget
- Your commitments: open accounts and repayments may be counted against how much you can borrow
- Your credit file: applications and missed payments may be recorded
Before you apply for a home loan
- Pay off and close BNPL accounts you don’t need
- Avoid new BNPL purchases for a few months before applying
- Check your credit report and correct any errors
- Make sure every repayment is on time
How a broker helps
Lenders differ in how they treat BNPL, credit cards and other commitments. We review your statements before you apply, flag anything a lender is likely to query and match you with a lender whose policy suits you. Learn more about our home loans, or read what LVR means.
Frequently asked questions
Does buy now pay later show on my credit report?
It can. Since BNPL was brought under credit law in June 2025, providers are licensed and many report to credit bureaus, so applications and repayment history may appear on your credit file.
Should I close BNPL accounts before applying for a home loan?
It’s generally a good idea to pay off and close accounts you don’t need. Lenders may count open BNPL limits and repayments as commitments, which can reduce how much you can borrow.
Will one late BNPL payment stop me getting a loan?
Not necessarily, but missed payments can be recorded and lenders will ask about them. A pattern of late payments is more of a concern than a one-off.
Talk to Peak Capital
Book a free 15-minute call with a Sydney commercial finance broker. We’ll tell you what you can borrow and which lenders fit your situation.
This article is general information only and doesn’t take into account your objectives, financial situation or needs. Speak to us or your accountant before making a decision.
